Pages

Tuesday, March 21, 2017

Rs.10 M, not too difficult in India for the average

While making $m in the US is not that difficult, making some money in India isn't that much of a hassle either. 

It's just the question of the attitude. If you have it, you can make it. If you are like the most, well, you end up like the most. We are not talking about those who already have plenty to take care of in their later years. The lower and the middle class are the ones who are most affected, and therefore, need to make arrangements for themselves. Someone said aptly, parents aren't emergency funds, and children aren't pension funds. You got to keep your individualism. 

In the absence of any social security system in India, it becomes all the more imperative that a person shows some wisdom in dealing with the finance. It is strange that bonded labor for life in employment is preferred to making slight changes to the behavior. Well done consumerism.

Let's deal with the finances of an average person in an average employment; yeah, it comes with an average salary.

In January 2000, Nifty was at 1592.20, with a PE lurking at 25.91; dangerous tread for a rational stock picker. By now, it appears that it isn't so for a rational equity buyer. If the index was bought as of January 2000 and held through December 2016, the annual returns would be 10%; not bad. If the investor had bought the index on a monthly basis instead, the annual returns would be over 12%. It would be slightly more, if we include dividends. 

So how can an average employee in India enrich oneself? Let's pick someone earning a salary of Rs.25,000 per month, with a spouse matching that sum. Not too unusual in these times; in fact, quite modest. Left to themselves, they would be swayed by the waves of consumerism, and would be bonded for life. Throwing caution to the winds comes natural to them. If only we could tame them, and teach them to behave, it would be a different life. Alas, we can't.

If the average couple can spend one salary for living costs, and invest the other salary, the value of their financial assets would be over Rs.16 m. Assuming they started at age 25, they would be quite fine compared to their own lifestyle by the time they are 42. At 6% average inflation, the present value of their assets is more than Rs.6 m. If the couple increased their investment by about 7.40% annually reaching Rs.84,000 per month in the last year, the value of their assets would be approximately Rs.27 m, and the present value of which would be Rs.10 m. Even when the growth in investment is matched to the inflation rate, the assets would be worth some decent money in today's terms.

Yeah, Rs.10 m is the number that is illusive to the lower middle class in India. Yet we found out that it is very much achievable. With that much of cash, the couple who worked only for about 17 years, can move on with their life. Chase their passion. One way that can be possible is to move to a place where housing and living costs are much cheaper. Life then is only fun. They can even continue to work, but on their own terms; choose the location, employer, work hours. The lower middle class too has the power to make life more purposeful.

Imagine what people who are better than the lower middle class could do. We see them everywhere earning decent salaries; yet, they are in the rat race, not able cope. When in fact they can be financially independent within 15 years of their work time, they choose not to. Getting pleasure out of self-torture?

If the couple, who are better off than the one discussed earlier, are able to invest Rs.600,000 annually, they would have more than Rs.12.50 m in today's value; this is made possible in 15 years, if the annual increase in investment is 5%. We are talking about someone earning Rs.50,000 per month, which is matched by the spouse. Such salaries galore in these times. Their investment in the 15th year would Rs.1.25 m. The formula is the same: save one salary, and invest the other.

I hear a lot of excuses. Instead of focusing on what they can do, they spend time on things that are not in their control such as the government, employer, and the workplace. They have no problems in spending on the status car, large TV, expensive cell phone, fancy gadget, and regular fine dining. Cash for investment purposes, heck, life is too short and momentous to dwell on uncertainties such as the long term; for them it is preferred gratification.

It is a simple trade off: A maximum of 15 years of deferred gratification, or work under someone else for life. Guess, what they pick. Like I said earlier, human behavior has reasons that reason cannot understand.

Tuesday, March 14, 2017

who's the winner in valeant

Bill Ackman's Pershing Square Capital Management held 18.1 m shares in Valeant as of December 2016, which represented 5.28% of Valeant, and was valued at $263 m. 


In fact, Pershing Square also held some call options to purchase 9.1 m shares. The total exposure to Valeant was about 3% of its $11 b assets under management. While Ackman had been defensively bullish on the investment, he has now exited the position entirely. 


The average price of investment was $196 per share, and the average sale price was $11 per share, a loss of over 94%. Such are the rules of the investment game; no mercy; no sorry; no thank you. The markets are never accommodating; they are as ruthless as one can be. 


Yet, Valeant was a business with some terrible economics. 


The market value of its equity today is $3.82 b, whereas its debt is $30 b. Almost of all its operating assets are owned by debt holders. With problems around, the economic value of $16 b goodwill becomes questionable too. Under the circumstances, Ackman was probably correct in exiting from this business. 


The equity was worth $88 b in July 2015 when the share price was $257.


Based upon the sale of 18.1 m shares and options equivalent of 9.1 m shares, Pershing Square must have incurred a huge loss on its investment. The loss, which could be anywhere between $3 b to $5 b, could have been avoided, but only with the power of hindsight. 

NY Times estimates the loss to be $4 b.


Bloomberg estimates the loss to be more than $2.8 b.


Whatever is the quantum of loss, it is quite significant to the assets managed by Pershing Square. Ackman also admitted this in his annual letter of January 2016:


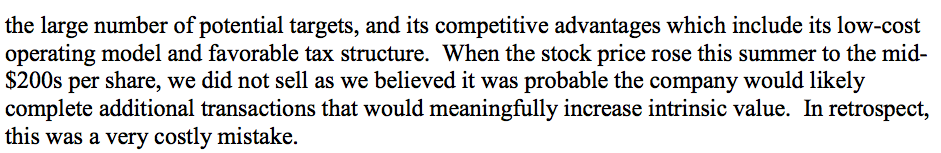
We cannot tell if greed, arrogance, or anchor bias was the reason for continuing to hold the stock despite negative vibes about the business. It could even be a rational theory that went terribly wrong; a mistake that Pershing Square and its shareholders need to forget, and move on.

Still, there is no dearth of long positions in Valeant as of now. Significant institutional investors include John Paulson (Paulson and Co) and Jeffrey Ubben (ValueAct Capital).


There is yet another battle to be won; again between Bill Ackman and Carl Icahn. This time on Herbalife. 

Who's going to win?

Sunday, March 5, 2017

how far apple can take you

Apple is worth $744 b now; just 34.41% away from becoming a $ trillion company. Next in line are Google at $588 b; Microsoft at $502 b; Berkshire Hathaway at $447 b; Amazon at $408 b; and Facebook at $400 b. Since Apple is already 27% ahead of Google in the run, we can assume that it could the first company to hit the $ trillion. Much credit goes to Buffett and Munger for not falling behind the technology companies in today's times.

The discussion is on Apple; so let me stick to that. The question is whether Apple would make sense for an investor at its current price.

The business
For the year ended September 2016, Apple had revenues of $215 b, on which it earned $45 b for its shareholders.


Over 60% of its revenues come from one product, iPhone.


Units are in thousands:


The key for this business is growth. Can its revenues, operating profits, and free cash flows grow at a meaningful rate in future? The law of large numbers is impending, although it enjoyed extraordinary growth in the past decade. Where can it possibly sell more?


Of course, the return for the investor is directly based upon its growth rate. iPhones are not going to be changed every year, although certain geeks engage in doing just that. iPhones, iPads, and Mac are not cheap. Growth in China and India is some possibility; yet, there is enough competition in the emerging markets. Fighting the price war is not going to be easy. Average price of iPhone is $645, iPad $452, and Mac $1,235. A large base and high price are a serious impediment to the growth story.

In the current interest rate scene, 10-year treasury is yielding 2.48%, and 30-year treasury, 3.07%. For an investor then the choices are: pick treasury at these rates, or look for something that is higher than that. I am not checking real properties, or high-yield bonds; that is a separate business. So let's stick to equities in the public market. And I am not going to calculate the cost of equity to precision with the academic formula.

I reckon, any rate that is higher than 3% should be sufficient, unless the investor is predicting higher interest rates. Even then how much higher? We can add an equity risk premium of say, 5 points to get to an expected rate of return of 8%.

Apple is a weird business. It is currently earning ridiculous amount of cash on virtually insignificant capital. It had $237 b of cash from $128 b equity and $87 b debt. That amounts to a negative operating capital employed. Yeah, it is a weird business.

The intrinsic value
In order to estimate intrinsic value of Apple, obviously, we cannot assume that such weirdness should continue. We have to assume that Apple will have to reinvest in order for it go grow. So there are assumptions regarding the revenue growth rates in the next decade, and beyond that, there is a cap on the growth rate until perpetuity. How much the revenues would be say, in a decade, $325 b? Tim Cook has a story, and so do you and I.

Apple has shown remarkable improvement in operating margins from 12.70% in 2006 to 27.84% in 2016, all thanks to the brand iPhone. Net margins gained from 10.30% in 2006 to 21.19% in 2016. Again, return on equity increased from 19.92% to 38.28%. For the reasons mentioned earlier, it is not meaningful to calculate return of capital. However, we cannot expect these margins and returns to improve any further or even remain unchanged in future. Apple has become truly large to sustain further improvements is a reasonable assumption. How far down will these be in a decade is anybody's guess. Are 20% operating margin and 15% return on capital until perpetuity defendable? Time, not Tim, should tell us.

As a consequence of higher reinvestment rate, lower growth rate, lower margins, and lower return on capital assumptions, Apple's free cash flows to firm should also be lower in the coming decade. How about $37-40 b for the stable business growth?

Based upon its intrinsic value calculated considering a myriad assumptions, Apple might even be successful in giving the investor a 7.50% return at its current price. However, following it has its pitfalls.

Perpetual cash flows
We can even assume that Apple has already matured, and can value it on a perpetuity basis. At $40 b of free cash flows growing moderately forever, I see that the rate of return to the investor based on its current price is about 7%.

The pricing effect
Pricing is relatively easier. Apple had an EPS of $8.31 in 2016, which grew 16% (in 5 years) and 38% (in 10 years) annually; exceptional. From now on, though, there would be bumps on the road; but how high to obstruct growth? At 5% annual growth, its EPS in 2026 should be $13.50. Apple has been trading at an average high PE of about 15, and a low PE of say, 10 in the last five years. If we mark its high of 15, its estimated price will be $202.50 in 2026. That is a return of 3.78%.

Then there dividends. If we assume that Apple will fall short of innovation and moves to return much of its cash back to the shareholders, and further assume that $200 b of cash, net of repatriation taxes, will be used up in the next ten years, the dividend per share should be $5.40 at year 10 without any equity dilution. The aggregate investment return (price appreciation and dividends) will then be just about 6%.

If we assume that Apple realizes its size and acknowledges that it can no longer innovate, and further assume that, consequently, it chooses to distribute all cash back to the shareholders, at $435 b of cash return during the decade, the aggregate investment return will be about 8.60%. At this rate, the dividend per share should be $10.40 at year 10 without any equity dilution.

This assumption also has its perils; the market might mark its PE down to lower levels; and Apple may not be able to generate another $200 b cash in the next ten years. Just imagine a return of $435 b of cash in dividends! That would be a voodoo. That would even be the end of story.

Buybacks
Apple could expedite share buybacks. $200 b can be used up to buyback 1.3 m shares from its shareholders. Sure, it would trigger market pricing if done at one go. Nevertheless, that should leave approximately 4 m shares outstanding. This should have an immediate effect of increasing EPS to $11. If this grows at 5% annually, EPS in 2026 would be $17.91. The estimated price at 15 PE will be $268 in 2026. That is a return of 6.72%. With increased dividends, the annual return could be in the region of 9%; much better.

All this assumes that Apple will be able to retain its existing earning power. Yet, is 9% a cap on Apple's returns for the investor?

The benefactor
Warren Buffett has been piling up on the Apple stock. That should say all is well for its business. Is that so? Buffett has also been piling up on the airlines stock. Yeah, that is the same person who said, if a capitalist had been present at Kitty Hawk in the early 1900s, he should have shot down Orville Wright. Yeah, the same airlines that grow rapidly, require significant capital to grow, and earn little or no money.  Yet, Berkshire's purchases have been like there is no other time. This time there is no 800 number to dial either.

Never mind, Buffett bought 61 m shares of Apple for $6.75 b as of December 2016; that is about $110 per share.


Subsequently, he also bought more shares of Apple, because he liked it.


These 133 million shares might have cost him at least $15 b, which makes the average price per share at about $113.


Well, these are worth over $18 b now; so he has already earned book profits of $3.5 b. The Buffett factor is also imminent in the market.

So what is it that he saw in Apple now that he did not see before? From a technology-hater to the 2.50% owner of a technology company, sure, there must be something. One could be the law of large numbers staring at him.

But here's the bizarre reason that he chose to give; some enlightenment I suppose.


Of course, the product is sticky; otherwise it would not have enjoyed the growth rate that it reported. It has been there since 2007, when iPhone was first launched. Granted, 2007 was too early to feel the stickiness; but, last five years would have told something.

Even Microsoft's windows and office have been sticky products since a long time. What stopped him from buying its stock, conflicts of interest due to friendship?

The enterprising Apple
What else Apple could do to please its shareholders? With $200 b cash and growing, it can create an investment portfolio with some high-quality stocks. It can acquire certain high-growth companies. There is no other business, presently, in the world that matches cash generating capacity that Apple has. That cash has to be employed such that its shareholders get a meaningful rate of return. Tesla is selling at $40 b; What about some of Google and Facebook? A diversified portfolio of high-growth technology, and high-quality stable business stocks, and some of the index itself will not be a bad idea. Then Apple will have two divisions, iPhones, etc. and company, and investments business. Tim Cook will have to look for a worthy capital allocator.

The trillion
If the $ trillion is what matters, here's what it takes Apple to reach it.


While irrationality knows no bounds, Apple is a 7.50% return stock. That's not bad considering the alternative opportunities available at this time. But, even the broader markets are capable of delivering that return, give or take some points. That leaves us to choose between a low-cost S&P-500 index fund and say, Apple. A comfortable, low stress market return, or an exciting Apple return.

That is the question.

Friday, February 24, 2017

$M, not too difficult in US for the average

The median income in the US in 2015 was $55,775; there are places where it is more than that. 


It is also true that average Americans cannot save enough to fund their retirement. This is why they also end up working in places otherwise they would not have liked to. This is also why they are sort of forced to take up work for longer years than they would have otherwise liked to. What a life! Even a masochist wouldn't like it. 

Someone said it long ago: Twenty years from now you will be more disappointed by the things that you did not do than those you did do. So throw off the bowlines. Sail away from the safe harbor. Catch the trade winds in your sails. Explore, dream, discover. 

It is an apt statement. Life is too short to stick to the comfort zones. Nevertheless, it is not very difficult to come out of it; neither does it take too long. The key is to become financially independent. Note that it is not being rich, which is actually relative. Someone with $500 k is richer than the one with $100 k; one with $1 b is richer than the one with $100 m. Talking in terms of the rich is not only useless, but also stupid. 

What we need to attain is financial independence. It is always measured in terms of how much cash one has compared to one's expenses. The higher the multiple, the higher the assurance. Someone with $100 k in financial assets and annual expenses of $10 k is wealthier than someone with $500 k assets and annual expenses of $250 k. To become truly financially independent, one needs to increase the multiple. 

There are only two ways to achieve an early financial independence: Increase income compared to expenses, or Decrease expenses compared to income. For most, it is much easier to do the latter; yet, they do not realize it. For them, life is to enjoy the moments on splurge. Little do they know that there is plenty of fun in delayed gratification. 

So how does an average person, employed with an average salary, become financially independent? If the two conditions are fulfilled, it is not very difficult: One, restrain; control; and behave. Two, invest savings in equities, preferably, in the S&P-500 index fund. 

In January 2000, S&P-500 was at 1394.46; in December 2016, it was at 2238.83. A 2.82% annual return over 17 years is no fun. Yet, the average employee could have become a millionaire by that time. 

It is because the markets are inefficient. They fumble on occasions; act irrationally at times. That's how they provide opportunities to the average employee. In February 2001, the index fell over 9% from the January 2001 value. 


Sure one could have bought in March 2001 and sold in April 2001; again bought in October 2001 and sold in November 2001; and so on. But we are talking about the average employee. In fact, here, we should be talking about everyone. It is very difficult to time the market on a consistent basis. Let's keep that story for another day. 

I am going to talk about the average 25-year old couple earning a combined salary of say, $50,000. Not very unlikely for the average. They are ordinary individuals, engaged in ordinary employment. How could they become financially independent? As we noted, it is easier to cut expenses than to increase income. 

If the couple saved and invested $2000 per month, which is $24,000 annually, in a low-cost S&P-500 index fund from January 2000 until December 2016, the total investment would be $408,000. Another way to see it is to keep one salary for living costs, and invest the other; there is not much excuse. Remember the buzz words: restrain; control; behave. It's possible. The investment value would be $707,000 as of December 2016 before the fund expenses, which are not too high in a low-cost fund. So the couple would be worth $707 k at age 42. The annual return changes from the paltry 2.82% to a more reasonable just over 6% due to the dollar-cost averaging, which happens thanks to the market inefficiencies. I have not included dividends, which if reinvested, should increase returns. 

They might say, the salaries weren't that much in 2000. It turns out that the numbers are not far off. If the investment was increased by 5% annually reaching $4600 per month in 2016, the investment value would be just over $1 m; not too bad. $4600 per month translates to $55,200 annually, which is the median salary anyway.

The losers might talk about taxes, etc. Remember, though, we are talking about creating enough wealth for the ordinary individuals early so that they too can let go of their shackles, and explore life. This is to show that it is very much possible for the average. The trade-off is clear: work for someone for life, or call your own shots after 15 years.

Their behavior is more important than income they earn. Cut costs relentlessly, and invest every month irrespective of the index value. After 17 years, at age 42, the couple could have $1 m in financial assets, which would also give quarterly dividends.

With $1 m plus financial assets, the average couple could move to a place where home and living costs are much cheaper, and have a fun-filled life. Why do they have to care to work for another unless of course they actually do love it? There is a superior life outside of the Bay Area and Wall Street too; and it can be more purposeful.

And now for the not-so-ordinary. If the couple can save $5000 per month, the investment would be worth $1.7 m. There are plenty of households whose annual income is $120 k. $5000 per month with 2% annual increases, i.e. $7000 per month starting 2016, would turn into investments worth $2 m.


Again, they might talk about the hindsight bias: where're the future returns?; Europe and Japan are already down; China is on the way; the US is not going to be an exception. Heck, these are the people who don't want to give up on the status car, large TV, expensive cell phone, fancy gadget, and those regular $5 coffee twice a day. If only they learn to defer their gratification, they would have to work, without choice, for only a maximum of 15 years.

But, heck no; human behavior has reasons that reason cannot understand.

Monday, February 13, 2017

buyback paradox at Infosys

Former CFOs of Infosys, who are also major shareholders, are seeking buyback from Infosys board in order to ensure proper use of its cash. They are right in questioning its capital allocation policies. 

That said, whether Infosys should initiate a buyback is a tricky matter. For a buyback to make sense, two conditions should be met. 

First, the firm should have excess cash. The business should be in a position to generate cash in excess of its reinvestment requirements. That happens when growth slows down, and it becomes a mature business. It looks like Infosys does have excess cash; it had Rs.345 b as of March 2016. This cash becomes free cash flow to equity investors if it cannot be used for working capital, capital expenditures, or acquisitions. The Infosys board should first assess whether it is the case; recall the CEO's grand plans for 2020. 

Second, the stock price should be lower than its intrinsic value. The value changes based upon the perception of the analyst though.

Price > Value: The former CFO considers that the stock price is expected to be lower, and consequently, generating lower returns to the shareholders; this is when the stock price is higher than its value. If the board agrees with this analysis, but carries out a buyback, which is usually at a premium to the market price, it would mean that cash is being used for a stock that had no growth prospects. This would bring down the value of Infosys as a business because of the purchase of an expensive stock. Any buyback of the stock would hurt the remaining shareholders, and therefore is not good for the firm. 

A better option for the CFO would be to sell the (expensive) stock at market price, and exit as a shareholder. Invest the proceeds in opportunities yielding higher returns. This will be good for the exiting shareholders, remaining shareholders, and the business itself.

Value > Price: If the board does not agree with the CFO's analysis, and considers that value of the stock is higher than its market price, the buyback makes sense. There is excess cash, and the stock price is cheap compared to its value. If the board carries out the buyback, the exiting shareholders (the CFO and company) would be worse off. This is because the stock having prospects of higher returns is exchanged for cash by the exiting shareholder. This would no doubt help the remaining shareholders; and that is the whole purpose behind a firm undertaking stock buybacks. 

A better option for the CFO then would be not to sell the cheaper stock back to the firm. Stay invested when the value is higher than price.

Whoever is right in assessing the value of the business will be the winner in this game. Heck, isn't this the case in any investment game?

Stock buybacks after all are dividend decisions. When there is excess cash, and assessing value of stock is difficult (if so the managers are not fit to run the business is another story), there is a much better option for the board. Payout higher cash dividends; even normal payouts accompanied by a onetime special dividend will be good.

Dividends are good!

Friday, February 10, 2017

infosys: shareholder value

Infosys is currently in news. This time it is up against its founding shareholders. They are questioning corporate governance at the company. 

After October 2014, when the founding shareholders left the company voluntarily, its affairs were handed over to the outsiders. The shareholders showed faith in the new professionals in running the company in a diligent, transparent and professional manner. The expectation was also that the new board and management will increase the shareholder value over time. 

As noted by them, after their departure, the founding shareholders did not interfere in either strategy or direction. 


There was no question of interference from any of the founding shareholders. Then there was this sloppy headline at the economic times:


However, when you click open the headline, this is what you get to read:


However, the headline coolly puts words in Pai's mouth to blame Murthy for the fiasco. It is evident from the article itself that Pai never said anything of that sort. We wonder why not do some clean reporting. In fact, Pai has backed founders in raising corporate governance issues at Infosys. 

Making significant severance payments to departing employees was not called for in the best interests of the company and its shareholders. This was the first crack. Furthermore, remuneration of the CEO not commensurate with the value being created was also questioned; the second. The remuneration committee is primarily responsible for it. 


With responsibility, there comes defense, which is human nature. Yet, not disclosing such a serious matter (excessive severance pay) in the annual financial statements was a serious breach of corporate governance. How could the audit committee overlook such an important matter?


Of course, the board is collectively responsible for this mess. 


And of course, it is a joke to bring in a legal firm to deal with the founders. 


The founding shareholders own over 12% of the business. It is only fair that their queries are addressed in a manner that is transparent and professional. The fact that their opinions are out in the open reflects how they are being treated by the board. 

I am surprised that Oppenheimer Funds, which owns 2.40% of Infosys, is not in line with the other large shareholders. What the founding shareholders have said, and what response Oppenheimer has given is another joke. The fund needs to know the difference between corporate governance and business strategy and plan. They are two different things, although one would expect the managers to have strategy that is not in fight with corporate governance. 

Of course, Infosys is the business of its shareholders. So what it is publicly listed? A 12% shareholder is a significant shareholder, not an apathetic animal in captivity.

Let's come to the management performance. Vishal Sikka took over in June 2014.


Infosys has done reasonably well in the past five years. Both operating profits and earnings have increased on a per share basis. Yet, the market value has not moved much from 2011 high.

Pai is not off-mark when he said:


It looks like the past performance was not satisfactory for the market. Clearly, market expectations are low with respect to its future performance; growth rates have reduced, and both automation and global, especially the US, trends are expected to drive down growth rates further.

Nevertheless, Sikka has grand plans for the business.


For 2016, the revenues were $9.46 b (Rs.624 b), and operating margin was 25.39%. If these targets are achieved, operating profits would be $6 b in 2020; in rupee terms, the value will depend upon the expected exchange rate. At Rs.70, the operating profits would be Rs.420 b as against Rs.158 b in 2016. Infosys was priced at a high of 17.80x EBIT and a low of 13.44x in 2016. If we take the lower value of 13x, Infosys could be priced at Rs.5460 b in 2020, which is only 3 years away. For the investor at the current price of Rs.2224 b, the annual rate of return would be close to 35%; phenomenal, assuming no dilution in equity. Any one interested?

As for the intrinsic value, I am not brave enough to do it as there are too many variables related to the future, which I am not capable of dealing with.

Sunday, January 29, 2017

demonetization of property and gold

There is still talk of demonetization; some in favor and some not. Cracking down on corruption and black money is a good idea. Whether demonetization will bring about the required change remains to be seen. That said, Indians no longer hoard most of their cash in the form of cash; both storage and security issues have caused them towards property and gold; of course, they were always the conduit. Yet, the proportion representing hard cash has significantly reduced, and that representing property and gold has significantly increased.  

So property and gold it is for the Indians. How to deal with that pretax cash diverted to land, building, and gold? Asking them to use aftertax cash rather than pretax is not useful; remember, it has not worked. Will asking them not to pay tax on capital gains work? I don't think it is a good idea. 

Why should people who deal in property and gold be treated differently from to say, a business owner? It would be like if you start a business, profits will be taxed. If you buy and sell either property or gold, profits will be exempt. Little funny, wouldn't it be? 

Investing is a serious business, whether in equities, debt, property or precious metals. The intention is to make profits out of the transaction; so that should make it a business. And it is a business, not any different, even for those who transact occasionally. When a home buyer for primary residence sells it after a decade or so, profits made are investment profits, albeit long term. 

Lack of regulation and bad intent of people have been the cause of this massive hoarding of black money in the form of property and gold. Crackdown on this is really important.

I haven't got nice things to say about gold; but have four suggestions, though. One of the best ways to stop corruption in gold is to tax it heavily; make it more expensive. It would also be additional income for the government. If people still want to buy gold, so be it. Second, every transaction on gold should be based on the PAN of the buyer; No PAN, no transaction. Third, increase the tax rate on capital gains. The idea is to pay heavy penalty by those who buy and sell gold. Fourth, all transactions should take place through banks such as cheque, net banking, and transfers. If someone does not have a bank account and wants to buy gold, that person got the priorities wrong. Needless to say, the authorities should keep an eye on the income of the buyer and buying pattern. 

It is a little different for properties. Investing in properties is a good deal. But in India, rents are not aligned to the market prices of properties. Due to this, the investor is brought to hope for increase in prices to offer reasonable returns. Excessive dependency on prices has made property transactions similar to that of a not-cash-generating asset. The investor will make money only when a greater fool is found. It is pathetic as investors are forced to overpay; blame it on the regulation. As prices seem high enough, buyers consider that using pretax cash is more profitable. It is a vicious cycle: black money channeled to buy property; consideration upon sale received in cash is again used to buy property; and so on.

Bringing tighter regulation is the key to deal with corruption in land and buildings. The single most important thing is to have a mechanism to track every transaction online. Make PAN compulsory for the transaction; I am not sure if it is there in rural areas when small plots of land are bought and sold. Reduce the complexities involved in capital gains tax on property. Bring rentals in line with market prices. For that to happen, value of the transaction should be included for registration purposes. Stamp duty and rentals are then based upon the market value. Again, make transactions through banking channels compulsory; cash cannot be used. Profits made on sale of land and buildings are investment gains; these should be taxed appropriately.

It would be an interesting idea if long term is when property is held for more than 5 years. And how about having a progressive system - short term<= 5 years; 5 to 10 years; 10 to 20 years, and more than 20 years - for capital gains tax?

Demonetization of property and gold, how's that!