Pages

Saturday, August 30, 2014

google's decade

The decade ago
On 18 August 2004 a not-so obscure company came out with its first time public offer of 22.53 m Class A shares at a price of $85 per share. Of this 14.14 m shares were sold by the company and the remaining 8.39 shares were sold by the selling shareholders, making the offer one of the biggest in history in dollar terms. The company collected $1.2 b in cash. The rest as they say is history. 

Google Inc. was incorporated in 1998. As the company itself puts it, Google is a global technology leader focused on improving the ways people connect with information. The mission is to organize the world’s information and make it universally accessible and useful. 

The decade after

Well, it looks like so far it has lived up to all that is said. Market value of its equity stands over $385 b today.

Google basically derives most of its revenues from online advertising. Other revenues consist of non-advertising revenues including licensing, hardware and digital content. 

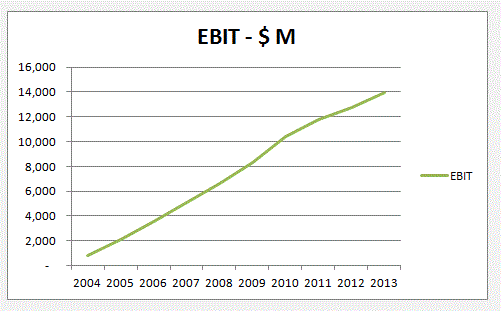
Google's revenue has increased from $3.2 b (2004) to $59.8 b (2013) and operating income from $840 m to $13.9 b.


Revenue composition in 2013 was as follows:


For Google, operating margin on advertising revenues are higher than on other revenues.


Return on capital has come down to a more reasonable 42.86% in 2013.


Pretax operating margin is steady at 23.34% (2013).


Google's share in international market has only increased. Now its revenues outside of the US is 54%.


Pretax income from domestic operations was $5.8 b and from foreign operations was $8.7 b in 2013.


Revenues
Most of its customers pay Google on a cost-per-click basis (Google AdWords), i.e. the customer (advertiser) pays only when a user clicks on one of its ads. 

There are also cost-per-impression revenues where advertisers pay Google based on the number of times their ads display on its websites and Google Network Members’ websites. 

Google distributes its advertisers’ AdWords ads for display on Google Network Members’ websites through its online program, Google AdSense. These revenues are recognized on a gross basis because Google considers that it is the primary obligor to its advertisers.

Revenues are poised to grow in future as online commerce takes off.

Operating margins and return on capital
We can expect its operating margins and return on capital to come down slowly in the next decade before they reach to more sustainable figures. How about 20% margin and 15% return on capital?

The cash.......trapped
Google has been hoarding cash big time. As of December 2013 it had cash of $58.7 b.


It can do a lot of things with that cash. It can buy Twitter for $30 b and LinkedIn for $27 b, or it can buy Tesla for $33 b. It is not likely, though.

As of that date, $33.6 b of cash was held by its foreign subsidiaries and was considered trapped, as this cash cannot be used for paying dividends, doing stock buy-backs or investments in US. Unless of course the differential tax (between tax rate where it was earned and the US tax rate) is paid on that cash before bringing it to the US. This is thanks to the US tax code.

Nevertheless, Google does not consider the cash as trapped because it wants to permanently reinvest outside of the US and its current plans do not demonstrate a need to repatriate them to fund its US operations.

This is a clever way of saying unless you change the tax code we will keep cash outside. Too many US firms are behaving in a similar manner of late as too many of them keep generating more cash outside of the US. The debate over being patriotic or just rational is getting hotter today.

Acquisitions and goodwill
Google has done a number of acquisitions over the decade; a cumulative $20 b of cash has been spent.

Click Holding Corp. (DoubleClick), a company that offers online ad serving and management services to advertisers, ad agencies and web site publishers, was acquired in March 2008 for $3.2 b of which $2.3 b was attributed to goodwill.


Motorola was acquired in 2012 for $9.6 b (net of cash taken over) which resulted in $2.5 b of goodwill. Motorola Home was sold in April 2013 for $2.5 b to Arris Group Inc. including a 7.8% ownership in Arris, and Motorola Mobility was sold in January 2014 for $2.9 b to Lenovo including some shares in Lenovo.


It is clear that Motorola was not the right candidate for synergy benefits.

The carrying value of goodwill is expected to generate cash flows of at least $11.5 b in terms of present value. Otherwise, it will be considered impaired, i.e. Google overpaid for its acquisitions.

Voting powers and control - Is it a fair deal, who cares?
Google has more than one class of shares. Class A shares with voting rights and traded, Class B shares with significant voting rights and not traded, and Class C shares without any voting rights (except as required by applicable law) and traded.

As of December 2013, approximately 92.2% of Class B shares beneficially belonged to Larry PageSergey Brin, and Eric Schmidt, which translates into approximately 61.7% of the voting power. 


In April 2014, stock dividends in the form of Class C shares were distributed (1:1 ratio) to the holders of Class A and Class B common stock. 

As of June 2014, there were 675.91 m common shares were outstanding.


It is very clear who controls Google, and if there are any further doubts, it is cleared in the form of the power of the board to issue, without stockholder approval, preferred stock with voting or other rights or preferences that could block any attempts of hostile acquisition. 

There is no chance that any outside shareholder would be able to influence corporate decisions at Google. None.


The next decade
Google is in a good position to take its best steps forward. As online business expands and emerging markets open up, there are immense opportunities to grow both in terms of size and value. Google has been reinvesting earnings back in its business with average reinvestment rate of 50.75%. It has also been spending sizable amounts on research and development each year.

How much it will grow in value in the next decade will depend upon how much revenues it will generate, how much it will earn in terms of operating margin and return on capital, how much reinvestment it will make, and the odds of making it.

Who wins this online warfare ultimately is any body's guess. However, as long as Google does not do anything stupid with its large cash the odds appear to be in its favor.

Will it live up to its current story line? Again as Google itself puts it, its business is characterized by rapid change and converging, as well as new and disruptive, technologies.

Tuesday, August 26, 2014

alibaba, the giant virtual mall

Gigantic initial offering
Shopping is becoming more technology-driven and purchases easier than before. As e-commerce expands over the globe and gives a platform for buy-and-sell the traveling costs should become lower. Delivery of goods and transfer cash where needed is only a matter of a click. When billions of people are becoming shopping-spree why not some of them become supply-spree? The sum of all activities engaged in business that is taking place online is poised to be gigantic. 

Alibaba group is one such big supplier who wants to get bigger. In May 2014, it filed its registration documents to go public in the US. With an estimated $20 b of capital raising it is touted to be one of the biggest IPOs in American history. 


Will investors buy into the Alibaba story? To check that let's have some background about the business

The tangled web of Alibaba 
Alibaba group is a huge shopping complex, a fairly large internet search engine (competing with Google), and a not-so-small bank all bundled together. 


The timeline:


  • Taobao Marketplace - online shopping;
  • Tmall - third-party platform for brands and retailers;
  • Juhuasuan -  group buying marketplace;
  • Alibaba.com - online wholesale marketplace;
  • AliExpress - global consumer marketplace;
  • Alipay - payment and escrow services for buyers and services;
  • Cloud computing services.

Alibaba and online China:


The players and the platform:


Logistics:


The story behind the pitch
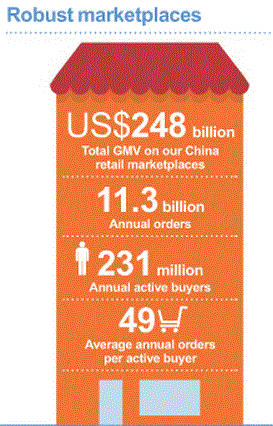
Gross market value of merchandise sold on Alibaba's websites (GMV) is reported to be $248 b which is much higher than Amazon ($100 b) and eBay ($76 b) combined.


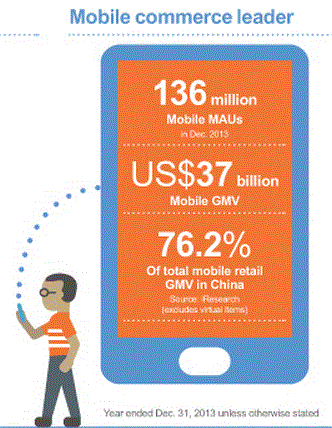
Of this, $37 b GMV came from mobile users.


That makes Alibaba the largest online and mobile commerce company in the world in terms of GMV. And the pitching does not stop.


The billionaires in the making
After the listing the current shareholders are likely to become wealthier by far.


It must have cost $280 m for Softbank to claim 34% ownership in Alibaba. For Yahoo it cost nothing to retain its shareholding because it collected much more from part sale of its stake than what it paid for the entire stake.

The tangled web of legal structure and contractual agreements
Because China has restrictions on direct foreign ownership the way is worked around such that laws are not compromised. These agreements in effect transfer most economic risks and rewards related to the business to the investors.


Composition of revenues
Alibaba primarily gets revenues from online advertisement and commissions; it also earns from fees, value-added services and cloud computing services.

A significant portion of revenues comes from online China.


Value of Alibaba
If Alibaba has to achieve what it aims to achieve success of this IPO is crucial. That means investors will have to buy into the story said so far.

Value of Alibaba is dependent upon its ability to monetize large online market and online consumer base of China in particular, and global in general. In effect it has the task on hand to convert market into market share, market share into revenues, revenues into operating profits, and finally operating profits into free cash flows. Can Alibaba pull it off?

The market for e-commerce has been enormous, and showing enormous potential for growth. If the following has to be believed, Alibaba had 83.76% (RMB 1,542 b) market share of the total China e-commerce of RMB 1,841 b in 2013.


Can online market grow as estimated? Specifically, can Alibaba continue to maintain its already dominant market share? Chances are lower on the latter, accordingly, we can expect the share to steadily come down in the years to come.

Operating margins
Alibaba's operating margins have improved from 25-30% range to the present margin of 48.1%. It is also unlikely that such a large operating margin can be sustained for long.

We can expect a few things going forward:
  1. China online market will continue to grow.
  2. Alibaba market share (GMV) will continue to slide from 84% to a lower, yet probably significant, share.
  3. Its gross margin (revenues as percent of GMV) is 2.6% at present; we cannot expect it to improve significantly.
  4. It will be difficult to sustain high operating margins for long; they will slide.
  5. No dividends will be in sight; Alibaba will have to spend lots in reinvestment each year.
  6. After a decade or so, it is more practicable to assume that both the total market and Alibaba will grow at a modest rate. In fact Alibaba should show signs of a mature firm. It could generate sustainable cash flows, pay dividends and do buy-backs, and have capacity to borrow more.
$200 b tech giant
Alibaba is soon likely to become one of the tech giants in the world.


However, there may be some gaps in this process of wealth creation.

I tried but concluded that to get to the value of $200 b Alibaba will have to do a lot of things - generate huge revenues and maintain margins.

The main issue is that we cannot attach high market share and high operating margins to Alibaba for too long. They will have to fall to a much reasonable and comfortable levels. And when we do that the result is a high implied growth rate to get to $200 b value of its common equity.

To know why consider this: Even when I let Alibaba enjoy reasonable excess returns until perpetuity (which I usually deter) during the stable growth period, I get year 10 revenues of $87 b. To get the right perspective we should translate those revenues into Alibaba's GMV and then into China GMV, and check whether the overall market (China GMV) appears to be achievable.

Two things to remember: There are caps on stable growth (perpetuity) period numbers; a firm cannot go on doing great things forever. Even during those great things period where growth is high it does not come free; the firm has to reinvest proportionately to achieve that growth. That reinvestment keeps a check on free cash flows.

Finally, it will be good to ask a few questions: how sustainable is this China story? Will there be any hiccups? For how long Tencent, Baidu, Amazon, eBay and others will let Alibaba keep those extraordinary returns? Are there any what if questions?

It has been thus so far: Jack Ma envisages and Joseph Tsai executes. Can these two make it to the next level?

Friday, August 1, 2014

flipkart gets global attention

The firm and its value
Flipkart was founded in 2007 spending Rs.400,000 on set-up costs. Today it is being valued at about $7 b (Rs.420 b) as a result of its recent capital raising. At least for these new capital providers the investment is about that big. 

That brings us to find out what kind of returns these investors are seeking. If we go by what the founders have in mind, that is about $100 b value in the next 10 years, the return is 30%. In 5 years it is 70%. Not bad, only if that happens.

Flipkart works with merchants to sell through its online platform (hosting third-party sellers) and earns a fee on sale. It is reported that the revenues last year were about $1 b and expected revenues this year are about $3 b; the growth is phenomenal. 

The market and its share
Nomura expects online retailing in India to reach $23 b in the next 4 years. China's e-commerce sales are pegged at $180 b currently which is 9% of the country's retail of $2,000 b, whereas India's online retail is less than 1% of total retail of $500 b. However, some expect that in the next 20 years it would be about 20% online. As per this report, online retail in India will reach $76 b by 2021 (that is 7 more years).

So it comes to two things: 1) Estimate the total retail market in the next 10-20 years; and 2) Estimate Flipkart's share in that market.

Revenues and margins
While revenues are growing, online retailers in India are not showing any profits yet. Revenues are one thing, but what really counts is the bottom line. Retail is a tough business. After all the years Amazon is not that profitable.

So how much can Flipkart get to where the barriers of entry are not that much? Amazon, eBay, Snapdeal, there could be many more in the competition, both local and global. 

Expecting that Flipkart would become profitable soon (how soon is estimation) is a reasonable assumption. However, the operating margins of online retailers are not very high. We can assign 5% pretax operating margin and 3.5% net margin. At present this is negative for the Indian online retailers. Return on capital for Walmart is about 16% and for Amazon is about 40%. Where would Flipkart be?

The $7 b value 
With starting revenues of $1 b, operating margin of 5% and return on capital of 25%, and a modest cost of capital, expected revenues in the year 11 would have to be $97 b for Flipkart to justify a valuation of $7 b today. I am assuming here that Flipkart is profitable from now itself which is not the case. There is also the assumption of the stable growth period where growth and margins are capped to more reasonable (stable) figures. The model shows that all the value is driven during the stable growth period because of heavy reinvestment that would be required during the high-growth period. Forget dividends; there aren't going to be any. In fact, Flipkart would have to raise capital a few more times during the period.

Amazon's revenues for 2013 were $74 b and for Walmart they were $466 b. From $1 b to $97 b in 10 years the revenues of Flipkart will have to grow at 58% annually. If the expected return (cost of capital) is higher (take your pick), revenues will have to grow at an astronomical rate; this is because revenues of $97 b will not be enough to justify $7 b. 

Of course, we can change any of the inputs and justify that, and that is left to anyone. 

Now, if we assume that in the next 10 years the Indian online retail market would be that of China's current, i.e. $180 b, Flipkart's share in the revenue would be about 54%. Can it pull it off? We just heard that Amazon is going to invest $2 b in its Indian retail operations. 

Alternatively, if we assume that Flipkart is not going to be profitable anytime soon, the model has to be revised. If we expect that it should take about 5 years to get to profitability, the minimum earnings will have to be about $1 b until perpetuity to get $7 b of market value of its equity. This assumes that Flipkart is in a stable growth phase until perpetuity which is really not the case, but the point is that you need those earnings to justify that value. Walmart had $17 b of earnings in 2013 and Amazon had $274 m.

The moral
The moral of the story is that I cannot value these firms since there are too many expectations to have beyond the boundaries. Having said all this it is kudos to Flipkart for getting global attention.

Wednesday, July 30, 2014

spice jet, not that spicy

If you run a bad business no amount of smartness can do any better due to the inherent qualities of the business. Yet, people don't care. The result?


How much income have these businesses generated for the capital providers? Or should I rephrase that question to why do people invest in a bad business?

A not-so-smart investor would have made 70% over the last five years and about 179% over the last ten years, while the airlines gave nothing but pains to the stakeholders. 

Spice Jet is in trouble; King Fisher is already in trouble; and Jet Airways is looking at losses and debts. We already know about Air India and Indian Airlines, but don't have information about the other airlines which are not publicly traded, but here is the picture: 


What are these airlines doing, building castles in the air? These businesses require tons of money on a regular basis, yet don't earn enough on that capital. If you are in a bad business, you generally can't help it, or help yourself. What a business it has been - large capital, losses; more capital, more losses - a global airline phenomenon.

Today, Spicejet is available at Rs.7.50 b; Kingfisher at Rs.2.50 b; and Jet Airways at Rs.28 b; Any takers?

Who is learning? Not many, we guess. Is that pride and status, or hubris?

Saturday, July 26, 2014

is tcs worth $85b

I have to admit that I am not a fan of technology companies simply because my background is not technology and I am not particularly interested in learning about what these businesses do.

Nonetheless, when an Indian outsourcing company whose business was skilled labor arbitrage is making headlines regarding its size, it is a matter of some interest.

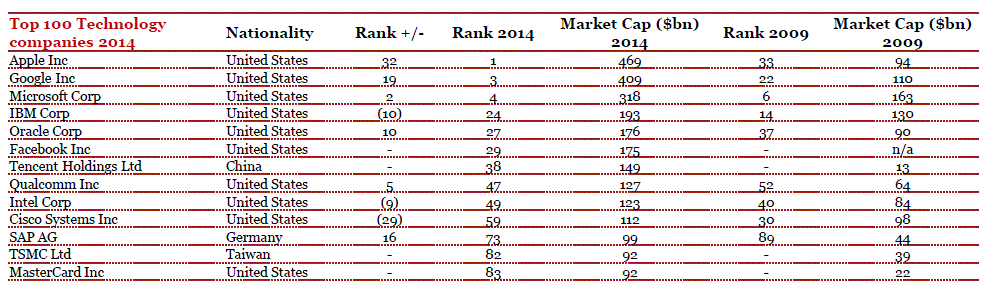
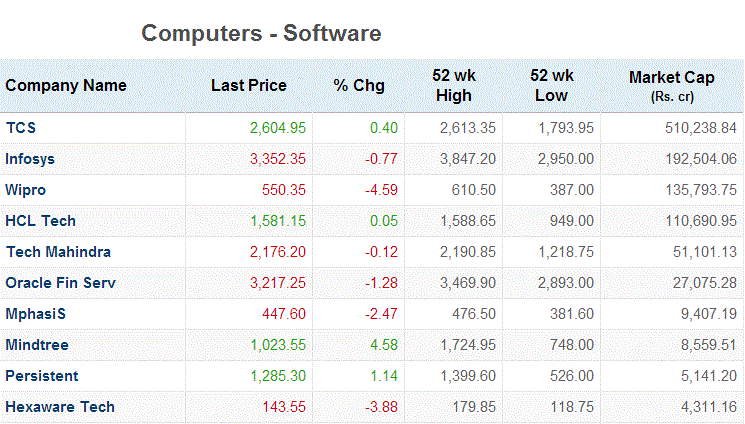
As per the PwC report the top technology companies by market capitalization as of 31 March 2014 are as follows:

I am not sure whether MasterCard is a technology business, that's not relevant though. Let's leave out TCMC as well. We have then SAP at $99 b of market value. Compare this to TCS which is now worth about $85 b (Rs.5,104 b). Is this a fair game? This report says that it could reach a market valuation of $100 b.

Before we discuss the story behind the game, let's look at some data.

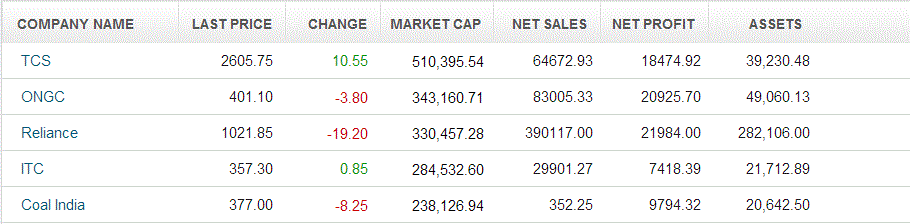
TCS is now by far the largest company in terms of market cap in India:


It has beaten its Indian competitors hands down:


Its stock performance in the past five years has been outstanding:


All the reasons to cheer for the shareholders. However, when market value of its equity was about $65 b in October 2013 I argued that it was overvalued. There is no vindication as yet. Who is going to talk to the markets?

I had asked, is TCS worth $65 b? Now the same question looms, is TCS worth $85 b? Let's check its fundamentals, that is, its capacity to grow its cash flows.

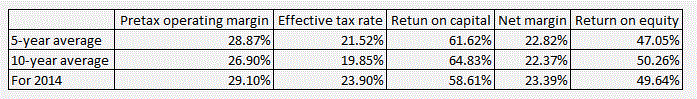
TCS has shown impressive margins and return on capital over the years. It has also managed to keep taxes down - with an average effective tax rate much lower than the marginal tax rate.


Its free cash flow to firm (FCFF) has grown from Rs.12 b in 2006 to about Rs.124 b in 2014.

There is no debate: Historical performance of TCS has been quite good, and naturally, the market has rewarded its stock too. Currently it trades at a PE ratio of over 25 which is close to its historical high PE ratio.

Our next analysis is to assess its growth rate and growth period - at what rate will TCS grow from now until it becomes a mature business, and when will it become a mature business? There are no easy answers to these questions.

There is another way: It is far convenient to question the market's valuation rather than making predictions (on cash flows and growth) on our own especially for an information technology business. So here I go:

Assuming that TCS will continue (will it?) its show over the next ten years - the current return on capital of 58.61% will be sustained over five years, reducing over the next five years to reach a stable period return on capital of 25% at perpetuity. Pretax operating margin of 29.10% over five years, reducing over the next five years to reach a stable period margin of 20% at perpetuity. Effective tax rate increasing over the period to reach the marginal tax rate at year 11 - to get to the current market valuation of equity at Rs.5,104 b, TCS has to grow over 26% in the first five years and over 15% in the next five years. I usually do not violate the terminal period assumptions on growth rate, margins and return on capital, yet, I do consider that perpetual margins and return on capital assumed for TCS are more than modest.

Now, we can rephrase our original question from, is TCS worth $85 b to can TCS grow at 26% in the first five years and at 15% in the next five? Also, can it continue to sustain its high operating margin and return on capital?

The market has its own reason:

It is left to the investors to make a call on this, although it is worth noting that its revenue should reach Rs.5,576 b in the next 10 years with those growth rates. Is that possible? Sure; but, I am not going to bet on that.

Tuesday, April 22, 2014

diageo's fantasy has a cost

Diageo is taking steps ahead to complete its acquisition of a controlling interest in United Spirits. The last time I discussed this was in February 2013 when acquisition of shares based on a preferential issue to Diageo at Rs.1,440 per share put a value on the total equity of United Spirits at Rs.206 b. 

Well, since that time much has taken place; some as envisaged, and some not as much. As of 31 March 2014, Diageo owns 41.83 m shares of United Spirits, and United Breweries Holdings owns 8.62 m shares. 

Subsequently in April 2014, Diageo has come up with an open offer to acquire more (37.78 m) shares at Rs.3,030 per share, a significant premium to its original plan. With this offer Diageo considers that United Spirit's equity is more than Rs.440 b; its current market value is about Rs.415 b. Just for comparison in February 2013 it was Rs.247.86 b. This 67% increase in the market value is due to the expectations that Diageo would increase its offer price; and it did.

Now let's discuss whether United Spirits is worth that price.

Based on the provisional numbers supplied, its book value of debt as of 31 Dec 2013 was Rs.77.94 b and it had cash and investments of about Rs.4.5 b. Its expected revenues based on extrapolation for the full year are about Rs.108 b. Over the last five years, revenues have grown by 17.87% annualized; good stuff, there it ends though. Its operating margins have been falling since 2008 which currently stands at about 7%. Operating income in 2013 was not sufficient enough to cover finance costs of Rs.9.8 b; fortunately, its other income has been substantial due to interest on cash, income from IPL franchise and other items. I am not sure why United Spirits presents income from IPL franchise as part of its operating revenue. Its return on capital is less than 4%. Since its 2008 acquisition of Whyte & Mackay assets United Spirits book capital has increased significantly. With no corresponding increase in operating income the return on capital is affected adversely; Its 2013 operating income was lower than that of 2008. Now Diageo has to offload Whyte & Mackay assets back to the market at lower than its cost as per this report.

I am sure Diageo must have thought something about United Spirits; probably as its playground to increase market share, may be; Or it could be just one more expensive acquisition.

To justify Rs.415 b value for equity we have to do some reverse thinking to get the implied assumptions involved in valuation.

However, even with robust and optimistic assumptions I have found it a bit hard to come around and think like Diageo in justifying this acquisition at the price offered which is in fact higher than Rs.415 b.

I used a much higher operating margin of 15% which except for 2008 it hasn't reached at least in the last eight years I have looked at; and assumed a very low effective tax rate to begin with and expected it to reach the marginal tax rate on a gradual basis. With these assumptions I checked what combinations of return on capital and growth rates are required to get the current market value of Rs.2,853.95 per share. In all the scenarios United Spirits is expected to reach the stable growth period gradually, and accordingly demonstrate the characteristics of a stable growth firm; this means naturally there is a cap on the growth rate and return on capital until perpetuity.

Here's how it looked:

For instance, at 50% return on capital United Spirits should grow at about 35.75% in the next five years to justify the current market price; furthermore, the return on capital and growth rate should still have to be higher in the subsequent five years, although these should become lower gradually until the firm reaches the stable growth period. This means United Spirits should have to display extraordinary return on capital and growth rates in the next ten years in order to justify the current market price. Alternatively, at 25% return on capital (which is way higher than what it is currently) it has to grow at about 53.75% in the next five years.

I also looked at Diageo's operating margin and return on capital which stand at about 30% and 19% respectively. At these rates United Spirits will have to grow at 47% in the next five years.

An important aspect which is often forgotten in zest is that for a firm to grow it has to reinvest certain portion of its after-tax operating income; without this any firm can magically get to the desired value, albeit on paper.

In fact, as the return on capital becomes lower reinvestment required by United Spirits to get to the market price becomes higher. At 30% return on capital, reinvestment required exceeds 100% which means value generated during the first ten years becomes negative, and therefore the entire market price has to be powered by the terminal value.

Because of this reason, any higher operating margins at return on capital lower than 30% (and at the corresponding growth rate) would actually bring the value lower due to the burden on the terminal value, and it not being able to compensate for the initial ten years of negative values.

However, when return on capital is 40% (with the corresponding growth rate) or more, higher operating margins would be able to generate higher value.

It is also nice to check revenues at year five and year ten arrived at based on any growth rate assumptions, and ask whether these are achievable considering the available market, competition and market share. I checked, but then decided not to plot them on the graph...

If Diageo considers that any of these (or any other) combinations is possible, there is more power to this deal.

There is no fine on dreaming, is there? Nevertheless, if the dream is going to cost the shareholders there should be some fine...but how much?

Wednesday, April 16, 2014

is it a bargain deal for sun pharma

Expensive stock acquires (cheap?) stock
Sun Pharma has agreed to acquire 100% of Ranbaxy in a multi-billion dollar deal. The transaction will result in a combined entity which will play a dominant role in the specialty generics segment.

Whenever an acquisition takes place it is justified with a number of arguments in its favor; the most common are: strategic advantage, control, and synergy.

Let's still ask the question: Is this deal good for the shareholders of both Sun Pharma and Ranbaxy? If it is not, obviously the deal is superfluous, waste of resources, at least for one firm.

First, this will be an all-stock transaction; which means there will not be any direct and immediate impact on cash. When an acquisition is done through stock it is important to know whether stocks of both the acquirer and target are expensive or cheap compared to the quoted market prices. Without this understanding we cannot conclude whether the deal is value accretive.

Just before the announcement Ranbaxy was quoting at Rs.459.55.


And Sun Pharma was quoting at Rs.571.80.


In accordance with the deal, Ranbaxy shareholders will receive 0.80 share of Sun Pharma for each share of Ranbaxy. Based on the stock price of each firm the transaction (exchange ratio) appears to be at the current market prices. 

We can see that both stocks have popped up in the subsequent days; Ranbaxy quoting at Rs.468.40 on 11 April, and Sun Pharma at Rs.627.20. Sun Pharma has shown more optimism to this deal though as the stock has rallied about 9.60% in four days. The market must be considering that the deal is a bargain for Sun Pharma. Is it so?

The past performance
Let's start with the market value of the firms before the deal. 


This is how the firms have performed:

Past 6 months:


One year:

Two years:


Five years:


Struggling Ranbaxy
Now let's move to Ranbaxy. I am not sure whether it has actually returned 147% in the last five years; in 2008 and 2009, the market value of its equity was higher. Even in December 2004 Ranbaxy's market value of equity was Rs.236 b; now it is pretty much the same, in fact a bit lower at Rs.196 b.

This is how it has moved over the years.


Let's not do any compounding; we know that it is not so good.

The 2004 annual report had the following forecast:


Its 2012 revenues were a little more than $2 b, and for 2013 a little less than $2 b.

Assumptions drive analysis
Ranbaxy's 2013 annual report is not yet released. That's some problem, but not much. With Rs.108 b of revenues and Rs.4.4 b of operating income in 2013, the pretax operating margin is only 4.10%; it was about 12% in 2012. This compares pretty low with Sun Pharma's operating margin of about 42%. Similarly, return on capital of Ranbaxy is about 8% compared to 45% of Sun Pharma.

It is only fair to consider that the current fundamentals of the firms would drive their growth for the next five years. After that it is expected that Ranbaxy would move towards better margins and return on capital, and both Ranbaxy and Sun Pharma would become stable growth firms.

With these assumptions, the gap between market values of equity of Ranbaxy and Sun Pharma which is currently about 6.52x should come down only slightly but not significantly if these are independently valued. This is simply because in the next five years Ranbaxy should grow at much lower rate and Sun Pharma at much higher, and thus already building a base effect.

Since these firms are going to merge going forward, the benefits of synergy, if any, can add value to the combined firm. Obviously, the value of Synergy will depend upon the assumptions related to the benefits of synergy. Sun Pharma might have made assumptions such that synergy benefits accruing to the combined firm would make the acquisition justifiable.

With a generous dose of synergy benefits translating into better margins and return on capital, the deal appears to be indeed a bargain for Sun Pharma. If synergy benefits were lower or not to be there, obviously the bargain should reduce.

The bargain lies in the future
In the final analysis it all depends upon how Ranbaxy shapes up in the coming years; better operating margins and return on capital, combined with adequate reinvestment, including in research and development, should increase the value of the combined firm. Will this happen? Sun Pharma would expect so.

Can Ranbaxy catch up with Sun Pharma in terms of margins and return performance? Sure it can, and if it does, it is a real bargain deal for Sun Pharma.

The bigger bargain
There is one thing that is clear: Sun Pharma is using its over-priced stock to acquire Ranbaxy which is struggling at the moment. This itself could be the the real bargain.