Pages

Thursday, October 18, 2018

suze orman gets it wrong, twice

Suze Orman, the personal finance guru and self-proclaimed queen of needs vs wants, gets it wrong about how much money you need to not to work rest of your life. In fact, she gets it wrong twice, first here, and then here. I am not taking anything away from what she has achieved; she has done herself well with net worth of $30 m as reported by the wikipedia. It was very nice of her that she even supported her mother and took care of her. More power to Suze. 

Yet, in her podcast with Paula Pant on 1 October 2018, Suze surprised me for not knowing the concept behind FIRE (financially independent, retire early), but still had her comments reserved for it: I hate it, I hate it, and I hate it. Sure Suze, you can hate it, but you need to know it before you hate it. And on 13 October 2018, she wrote a post on Linkedin where she noted that she was given bad information about FIRE. Well, we could ask her, by who? Never mind. 

In the podcast, Suze goes on about how wrong FIRE is about finance and work. She says, it is not possible to live well if you do not have $5 m or $10 m. She also mentions that the retirement age for people should be 70, not any earlier. According to her, $2 m is nothing but pennies. Never mind that the US median household income for 2017 was $60,336. How many people can afford to spend $2 m on their family medical needs (which Suze did)? 

First, there must be others who have spent more than $2 m; but they are exceptions, rather than the norm; they are some very rich people. Second, more important, you need not, and even Suze did not have to, spend $2 m on medical costs. That is because such needs are to be taken care of by insurance. If you think that you need high insurance, take one by paying higher premiums. There are people who think that a much lower insurance is enough. For them, basic, standard insurance will be just fine. For every calamity you think you might face, you are entitled to, and should, take an insurance. Accumulating cash just to deal with it is both unnecessary and unwise. 

The same goes about the size of financial assets. Who are we to generalize and say that $5 m, $10 m, or more is required before one can retire? To each his or her own. If Suze requires $30 m before she can afford not to work for money anymore, great for her. If Spendy thinks she requires $100 m, more power to her. On the other hand, if Frugally's idea of enough is $1 m, we cannot much argue against that either, can we? 

The key is that the financial assets will have to be reasonably sufficient compared to the person's sustainable annual costs. If a family's annual costs are $20,000, having $1 m in financial assets covers a period of 50 years assuming zero real rate of return. I can safely say that it is enough. I can also see that while Suze may not be able to live on $20,000, someone else might live on that quite happily. Wouldn't it be wrong on anybody else to pass a judgment on that? 

The same can be said about having $40,000 costs and $1 m assets. People who are aware of basic math and some knowledge of finance should be fine with this situation. This is how it should work: In the normal times, the family will spend $40,000 in annual costs adjusted for inflation; in down markets though, the family will learn to bring down the annual costs; substantially down if required. You see how a flexible family can adjust, yet live happily if it wants to. Suze will not understand it, forget appreciating it. She even missed that these people's math is based upon compounding over a long period of time. But I don't blame her because she has much more money; it is difficult to think different in such a situation. 

Yet Bill Gates, the richest man at the time, said, beyond a million dollars, it's the same hamburger. He may have said it in 2011 (or I don't know when), but the hidden meaning from it holds good all the time: That you do not need a fortune to live well. What you do need is the right mindset. If you lack it, we cannot help it. 

Don't get me wrong; it is great to have $10 m or much more. But like everything, it has a price tag: How many hours of work, especially that is not enjoyable, will one have to spend in order to get it? For instance, if one is able to get that number at age 60, after 40 years of selling time, what good will that $10 m or $100 m do to him or her? Heck, the precious time is already lost; that's a huge opportunity cost. If that person is fine with $1 m at age 40, what's wrong with it? In fact, here's what is good with it: That person can spend rest of the life in doing things that are fun. Who cares if that does not bring more cash? Doesn't it bring more gratification and pleasure? 

Suze implies that $200,000 to $400,000 is what one requires annually to live. I am not sure how many will be able to afford that even after 40 years of labor. Then there is this statistics that tells us the number of millionaires in the US. Their definition of millionaires: households with at least $1 m in investible assets, excluding primary residence. As per the report, there were more than 11 m millionaire households in the US in 2017. That means we have about 115 m households that are not millionaires. Of course, the concentration of wealth in the hands of high net worth households is disproportionate. So what should these 115 m households should do, go after $10 m, or fun and happiness?

The question to ask is: After basic needs can be taken care of by the cash that you have, will you be happy working just for the sake of more money or on things that really make you happy in life? The endgame is actually about happiness, not cash. If someone likes photography, not coding, what good that extra cash from coding do? That person will be happier in life, and therefore more successful in life - (happiness is success) - with photography. That is basic commonsense, but not many are capable of pursuing it.  

In her Linkedin post, Suze acknowledges that not working in a place that is not enjoyable is a good idea. But then she says that one has to look for another place so that it can bring money. For her, having 25 times costs and retiring at 40 without working is too risky which will not work for 50 or 60 year period. 

The thing is that these FIRE people are a bunch of smart people. They know the math, finance, and logic behind their choice. In fact, the RE is actually a misnomer; retire early is not retire from work altogether; it is retire from unwanted, not enjoyable work; it is a choice to retire from working for money; there is no obligation at all. None of these people have the idea of sitting idle in life. They want to do work that is both meaningful and fun for them; and they want to keep doing this for the rest of their life; there is no retirement from this work. If this work brings money great; if it doesn't it is fine. But mostly, there is some money coming in that contributes to their bills. Some even like the idea of taking up part time work just for bills, and use rest of the time for fun. There are too many possibilities; but sucking thumbs is not one of them. 

Basically, the FIRE people are frugal which gives them immense power and option to adjust their lifestyle according to the needs of the time. Spending $2 m on medical costs is not one of them; they will buy insurance for it. They know that oatmeal and rice-n-beans isn't a bad deal if combined with fun-filled day's work. Being financially independent is a very powerful idea. They have time for leisurely meals, for healthy meals that cost less, for workout, for work that they like, for good sleep, and for all the fun in their life. If they chased many millions of dollars instead, they wouldn't be able to do any of this. They are more likely to be happier than others, although I agree that happiness is relative and elusive. 

May be it should not be called FIRE, but FIFA (financially independent, fun all time).

Wednesday, October 17, 2018

investment seminars, bullshit

I was talking to a friend of mine, and she asked me the question: why don't you attend investment seminars? Here's what I told her:

It has become a fad to organize investment seminars, lectures, and workshops where the organizers bring in some of the well-known people from the investment industry and ask them to talk. Twin benefits there: The talkers earn, and the organizers earn more. What a scheme there.

I really don't like anyone charging money to others in the name of giving investment advice. I have made it quite clear here, here, and here. They are such a bunch of assholes that I am not surprised, but have to despise them for what they do. If they had any shame and self respect, they would be taking up an honest job to pay their bills. Heck no, they like to loot people who are naive, ignorant, and probably greedy too. Then it becomes easy for the talkers to actually extract from them. 

I don't care attending seminars and workshops even if coming from the best of the investors, especially if it costs. I like to learn investing because I want to make money, and my idea of that is simple: read and observe; that's about it. Even the markets teach us periodically; even if its lessons are repetitive, they carry meaning and require timely reminders. There are news and factual stories about businesses, business managers, investors, traders, and so forth everyday. I make it a point to read at least some of them. There are quarterly and annual reports from businesses to read. There are business and investment books although I don't like to overpay, for there are enough of them available at cheap prices. There are plenty of free and cheap sources to learn. Everyday, there is something to learn. So a learning mindset is more important than listening to crap stories that are to be paid for.

Here's why it is so easy to make reasonable amount of money by not paying a dime. 

For the average US investor
Select a low cost, diversified equity index fund (S&P-500 is good enough), and throw cash into it each month. Do this for more than a decade, preferably for two decades, and you will be good.

You will be better off than most of the money managers out there trying to beat their trumpet; they will struggle, but you will be fine. 

For the average Indian investor
I have 3 options for the investor; choose any, but stick to it for a long time.

Option1: Select a low cost, diversified equity index fund (Nifty-50 is good enough), and throw cash into it each month.

Option2: Select a low cost, diversified equity index fund, a large-cap equity mutual fund, and a mid-cap equity mutual fund. Preferably select funds from different, reputable organizations. Throw cash in the ratio of 40:40:20 in these 3 funds each month for a long time, and you are done.

Option3: Select a low cost, diversified equity index fund, 2 large-cap equity mutual funds, a mid-cap equity mutual fund, and a multi-cap equity mutual fund. Preferably select funds from different, reputable organizations. Throw equal cash in these 5 funds each month for a long time, and you are done.

The above is a no-brainer strategy, but has the power to beat many of the money managers. More importantly, you will be able to earn returns better than alternative opportunities and will have enough to be happy, although happiness is a relative term.

For stock pickers
It is a different story for the stock pickers. But, what is certain is that even they don't need seminars and workshops. Seriously, I find the talks quite boring and also unnecessary to mankind. Most of these talkers earn through other people's cash; so imagine, how pathetic their ideals are and ideas will be.

Investment seminars and workshops
Shun them, abhor them, mock them, for they deserve it. You and I do not need them. If you want to have some laughs on comedy, attend that are available free of charge. But then remember, your time is valuable. If they cost a dime, you know what I mean, you have a reason to chuck them. All I can say to end is, caveat emptor. They are all there to loot you, be careful. 

Thursday, October 11, 2018

s&p-500 real returns, not 7%

Most early retirees bank on the safe withdrawal rate of 4% for their financial assets to last their entire (well, almost) life. This rate was backed by the Trinity study carried out in 1998. So the aspiring early retirees vouch by the study, and declare their financial independence once their financial assets reach 25 times their sustainable annual expenses. For instance, if the current annual costs are $40,000, the required cash to be financially independent is $1 m. 

This is how it goes: While the annual costs increase by the inflation rate each year for the retiree to sustain, investment returns exceed inflation rate by some margin. The assumption behind this is that the assets are invested to yield a real return of 7%, and therefore, a 4% withdrawal rate would almost never deplete their portfolio. The 3% difference is the cushion that protects the portfolio and even helps it grow. 

The purpose of this post is to check whether the market's real returns are 7% in the long run. Let's assume that the retiree invests entire cash in the total market index of S&P-500. Here's the story:

The first thing to note is that returns without dividends reinvested are lower, mostly by about 2%.  More importantly, the real returns are mostly lower than the expected return of 7% when dividends are not reinvested.  That should affect the 4% rule significantly. 

for today's early retiree


I have collected the 40-year period data to check the actual returns of the S&P-500. An early retiree usually will have 30 to 40 years of financially independent life. If one were to retire now, the past data suggests that if dividends were not reinvested, the real returns were lower than 7% during all of the past periods except from January 2013 to date. Even after dividends reinvested, there were 2 periods when the real returns were lower than 7%. In fact they were much lower 3.58% (from January 2000) and 5.12% (from January 1998). This is due to the dotcom buildup during 1998 to 2000. However, the past 5-year returns have been excellent; real returns exceeding 12%. This is mainly due to the financial crisis of 2008 which supplied much lower base to recover from. Which one of this we would like to expect on a more sustainable basis in the next say, 30 or 40 years?

for 2013 early retiree


For those who were looking to retire in 2013, the data is more interesting. None of the years showed more than 5.50% real returns before dividends. Even after dividends invested, the information is scary. Only on 3 occasions did the real returns exceed 7%. I am sure the aspiring retiree would have thought a bit before concluding that the markets would yield expected real returns of 7% in the subsequent 25, 30, 35, or 40 years. Past information did not much support this claim. 

for 2008 early retiree


The story is not very different for the 2008 retiree. Even after dividends reinvestment, the real returns are far behind the expected 7%.

for 2003 early retiree


I wouldn't bet on the 7% for 2003 aspirant as well. The past actual real returns were not very comforting to conclude that the expected real returns were going to be 7%. 

what to do then
I am not going to argue against 25 times number because the word early retiree is actually a misnomer. Nobody sits on the couch sucking thumbs during the financial independence years. That person is more likely going to be doing something of interest and passion which usually translates into money. So it is more likely that bills are going to be paid by the money earned through matters of fun rather than withdrawing from portfolio. Some take up part time work just so that bills can be paid. Most find ways to earn cash and not touch the portfolio. That makes sense. 

Yet, my take on the required cash is a bit different. I like to assume a zero real rate of return on the portfolio. After that, the math is easier and is a function of annual costs and number of years. For annual costs of $40,000 and 40 (expected) years of financial independence, the required cash is $1.6 m. This is 60% higher than that is expected by the 4% rule, but more conservative and more certain to last. 

I reckon the financial independence aspirants will be better served if they tone down their expected returns from the equity market index. In fact, when the allocation is between both equity and bonds, the expected returns fall much lower. Then the 7% real returns becomes a farce. 

Thursday, October 4, 2018

yes bank's september

Never mind what happened to the Indian markets today. The nifty-50 fell 2.39% to end at 10599.25. Yeah it fell yesterday too. Let's keep the index story for another day. On 6 September, Yes bank traded at a high of Rs.347.80. On 20 August, at a high of Rs.404 per share. Things were looking alright for the bank until 21 September. The day before was a market holiday. On 19 September, the stock closed at Rs.319.20.

On the same evening, the bank reported that the RBI had rejected its request to extend the CEO's tenure by three years. The next trading day on 21 September, the stock tanked 29%, and closed at Rs.226.50 per share, equivalent of a loss of Rs.213 b in market value. Can one person be so important for a publicly traded, large banking business, or was it just the market's whims? The quantity traded on that day was over 293 m on the NSE, compared to the average of less than 30 m during the previous seven trading days.

As per this report of that fateful day, the bank was cited three reasons for the RBI's deadline for the CEO's tenure until 31 January 2019: Weak compliance culture; Weak governance; and Wrong asset qualification. The allegations seemed too brutal, and the bank made a new low of Rs.197.25 on 25 September when the board was to meet for the future course of action. 

However, 28 September was more special when the stock quoted at Rs.165 at some moment, but closed the day at Rs.183.65 per share. The market capitalization of the bank stood at Rs.423 b, some 54% down from its August's high. Too much, too soon? Is the market crazy, or is there more to this?

As of June quarter, Yes bank had impressive performance to show: Gross npa 1.31%; Net npa 0.59%. Net npa, security receipts and standard restructured assets totaled 1.52%. Yet, herein lies the catch. If these numbers are good, at the current price of Rs.215 per share, the stock is trading at 2.15x its adjusted book, a reasonable price having potential to yield better returns in the next 2 to 3 years. 

If the asset quality is worse than it is reported, it becomes a little complicated. The value becomes a function of how the book looks like. For instance, if the net asset quality is worse off to say, 3%, the current price becomes 2.50 times its adjusted book. If 5%, the price will be 3.19 times the adjusted book. Naturally, the returns will be impacted. That is why the management trust factor is so important when it comes to valuing banks.

The bank's capital raising plans have been held up because of the story that has unfolded. At the moment, therefore, the capital ratio is not the best which means the bank's near term growth will be somewhat subdued. After new capital, the bank should be able to move on to the growth path. Its return on assets (1.35%) and return on equity (16.40%) are pretty decent. There is a reason to believe that this should continue. 

On 1 October though the bank released its unaudited details for the latest quarter, and noted that its gross npa were stable compared to the previous quarter. 

In the meantime, there is no dearth of recommendations:


Time will tell whether Rs.215 is a good buy, or a great buy, or something else. It looks like there is an opportunity here for the investors if they are willing to show some patience after picking it. 

Tuesday, September 18, 2018

lehman, financial crisis 2008, and more

Lehman's history
Lehman Brothers was founded in 1850, and became an important trader in cotton during those times. Later it focused on trading and brokering of commodities. The firm dealt with great depression, and came out having survived. The business of venture capital and underwriting of capital issues was steady and successful in the subsequent years. By 1975, Lehman had became a prominent investment banker for the American businesses. 

American Express acquired Lehman in 1984 for $360 m to form Shearson Lehman American Express. In 1988, the firm merged with EF Hutton stock brokerage to form Shearson Lehman Hutton Inc. 

Before the initial public offering, the banking and brokerage operations were divested of, and retail brokerage and asset management business was sold by American Express. Lehman Brothers Holdings Inc. became a publicly traded firm in 1994 with Richard Fuld as its CEO. His 14-year stint as CEO had to end with filing for bankruptcy on 15 September 2008. Before that, the firm fended off rumors of cash crunch due to the collapse of Long Term Capital Management in 1998 as fake news. By 2007, Lehman had posted record revenues, earnings, and earnings per share for four consecutive years. Fuld became a hero after leading the firm to post 14 consecutive years of profits after it had reported a loss of $102 m in 1993. Little did the market know of the amount of leverage used to drive returns on equity. The asset management business was revived in 2003. In 2007, Lehman had revenues of over $19 b and posted record high earnings of $4.2 b. 

Perhaps things would be fine had it not ventured into the lower grade mortgage lending business. Of course it was lucrative, and seemed like a good idea at that time. The Alt-A mortgage, considered lower than prime but better than subprime, began after Lehman acquired Aurora Loan Services in 1997. Later in 2000, BNC Mortgage LLC was acquired, and Lehman became a subprime mortgage lender. These lower grade, higher risk mortgage lending operations had a stunning growth story: Lending in 2003 was $18.2 b; in 2004, it was $40 b; and in 2006, both Alt-A and subprime loans comprised more than $40 b per month. Quite naturally, Lehman started 2007 with too much of risky assets supported by too little of equity. Any good year with this capital structure would yield enormously high earnings for common shareholders; and it did, in 2007 of about $4.2 b. Any bad year would be of enormous losses. And a very bad year, would let the course to bankruptcy; and it did in 2008. 

2008 operations
The winding down of BNC subprime operations in August 2007 perhaps came a little too late. Consider this: Lehman posted profits of $489 m in the first quarter of 2008. Citigroup posted losses of $5.1 b, and Merrill Lynch had $1.97 b losses. In the second quarter though Lehman reported record losses of $2.8 b which came after a very long time. Revenues for the quarter ended May 2008 were $6.240 b, and interest costs alone were $6.908 b. It had $6.513 b of cash available for operations. Total assets were $639.432 b, of which $13 b was cash deposits mainly with the regulatory authorities. In effect, its net operating assets were: Financial instruments and securities of $269 b; Collateralized agreements of $294 b; and receivables of $42 b; totaling $605 b. You couldn't do much with property and equipment ($4 b), intangible assets ($4 b), and other assets ($5.8 b). During the quarter, Lehman lost $17.899 b of cash from operations which was made good by debt.

In June 2008, Lehman raised $4 b of common stock at $28 per share, and $2 b of non-cumulative preferred stock carrying 8.75% coupon, which had a mandatory convertible clause. Apparently, this capital raising was not good enough because its statement of financial position as of May 2018 looked like this: Assets ($639.432 b) financed by common equity ($19.283 b), preferred stock ($6.993 b), and debt and other payables ($613.156 b). Just 3% common equity meant that asset losses of only 3% would wipe out entire equity; a very vulnerable situation to be in.

The auditor's report dated July 2008 based on their review of May 2008 (quarter) operations, and the report dated January 2008 based on their audit of November 2007 (year) operations, expressed unqualified opinions on the financial statements. There wasn't a note on Lehman's going concern issues.

Lehman reported Tier1 capital ratio of 10.7% and risk-weighted capital ratio of 16.1% as of May 2008. This wasn't reflective of the risks that the firm was up against. As long as property prices remained high it was fine. If prices were to fall, Lehman would need cash to make good on margins to its lenders. When prices came crashing, the firm would need significant amounts of cash on short notice. Inability of the original individual mortgage borrowers also had a role to play which had cascading effects on property prices and consequently on the bundled mortgage assets prices; there was a reason they were called subprime.

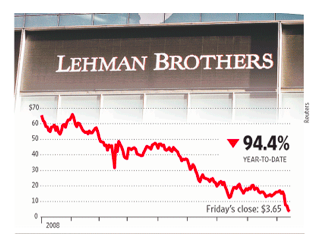
Lehman stock prices started falling, and the subsequent downgrades on Lehman by the rating agencies meant its derivative contracts demanded billions of dollars in collateral. By 9 September 2008, Lehman was worth only $6 b while it began 2008 with a market capitalization of over $35 b.


Nevertheless, here's the thing: If the markets trusted on Lehman's ability to recoup, even if it were to take a long time, it would have been ok. However, it was not to happen. Lehman lost on its credibility to raise short term cash, and there was no other choice. 

No bail out
Even the government turned the other way. It would rescue Fannie Mae and Freddy Mac; both firms had owned or guaranteed about $6 t of the total $12 t US mortgage market. It bailed out AIG. It also facilitated the $50 b Merrill Lynch buyout by Bank of America. But not Bear Stearns and Lehman. The first to go was Bear Stearns when the government let JPMorgan Chase buy Bear Stearns for $2 per share. Warren Buffett bailed out Goldman Sachs by investing in its $5 b preferred stock carrying 10%, which helped boost the firm's credibility and made its capital raising easier. All the firms that survived were beneficiaries of the government's $700 b troubled assets relief program bailout. 

Of course, the government thought Korea Development Bank would rescue Lehman. When it did not, the stock price crashed below $8 per share. It also hoped that Barclays would buyout Lehman which did not happen thanks to the veto of the UK regulators. 

Then the bankruptcy was made inevitable; 15 September 2008 and Lehman became part of the history being the largest bankruptcy of all time.


The S&P-500 fell more than 4.5% (source: Yahoo finance) on the day, and so did the Dow Jones which fell from 11421 to 10917.

Bankruptcy meant $0 stock prices, and this is how they panned out.


Subsequent to the filing, Barclays bought selected US assets for $1.29 b, and Nomura bought Lehman's Asia operations for $225 m, and parts of European operations for nought ($2 nominal). 

What if
I sometimes wonder what would have happened to Lehman and the financial markets if the US government had bailed it out. That is to supply cash and fill liquidity, and own equity until Lehman was able to get back on its feet. When asset prices and markets recovered, as they did, Lehman would repay its debt (equity) back to the government, and either remain a privately held firm or issue shares to public to operate as a listed entity. Alas, it wasn't to be. And we have a number of lessons to learn. 

Lessons that markets don't learn
The first and foremost is never to be at the mercy of someone else. This position of weakness is almost always caused by excessive leverage compared to own capital. The second is never to trust the governments to come and support during desperate times even while they choose to discriminate. The third is never to be in a business that is mainly dependent upon hope, greed, and the greater fool; most likely, the business itself would end up being one such fool eventually. Lehman, along with other firms that fell, unfortunately did not have the time to learn these lessons. Yet, I hope that those firms that did survive have learned. But then, don't we know that what we learn from history is that we don't learn from history?

Thursday, September 13, 2018

stocks for long

The Indian markets have had downward movements in the last few days mainly due to the fall of rupee relative to dollar; but there are always other factors too. The media, as usual, has been going crazy, and naive investors are wondering whether to buy, sell, or keep quiet. Someone said it long back: it is human nature not to be able to sit quietly in a place. There is nothing new here, or elsewhere. The US markets have not been any different. 

While I note that it is possible to find stocks to buy in every market, bull, bear, or volatile, there are times one could do well if one was able to sit quietly for sometime. In investing, there aren't exact rules to follow other than this one: buy low, sell high; or sell high, buy low. There are many ways to achieve this. The game is therefore more of an art than science. 

People think that they can make money by always being active in the market. Yeah, they can, but the chances of consistently being successful in the long run is much limited. That's the reason why there have been very few successful traders and speculators. If we check investing patterns of the rich, we can find that most of them did well by staying in the game for a long, long time. Many of them have had almost all of their wealth tied to one or two businesses, and yet the outcome turned out to be quite good. The reason is simple: they focussed on their businesses rather than anything else. 

It is stupid to argue about things that are not in our control. For instance, oil prices and currency fluctuations. We have witnessed these things, and more weird ones, in the past. Yet, businesses have prospered. It is therefore much better and easier to concentrate on the businesses we like, pick the stocks, and be part owners and enjoy the ride as long as we continue to like those businesses. Let the managers worry about how to deal with: the operating, financing, and dividend decisions. When businesses are good and managers are honest and able, there is little we can and should do to alter. Buy right, and sit tight: There is much money to be made when we don't interfere with the compounding math. 

Alas, not many can understand this simple, yet powerful game. Get rich quick is what lures them; nothing can be worse than one's neighbor getting rich. Even Gekko would have probably agreed that envy is worse than greed. 

When markets are overpriced, it is better to pick a book or go out. When they are underpriced, it is better to buy our favorite businesses at prices that we like. When markets are volatile, either sit quiet, or simply set up a program to buy the index itself periodically. In fact, index buying is great for people who do not understand the game. Such buying will ensure that prices are averaged out and returns are satisfactory. The only condition is that the index buying period should be continuous and for a very long period. 

Of course, there are times when I like to indulge in trading. After all, I find markets fun all the time. The capital allocated to trading is tiny, but it lets me have fun. And that's the key. We should not allocate a significant amount of capital to speculation; that will be silly. 

It is easy to summarize: Select the businesses that we like to buy. Wait for the right price; let the wait be for long, no problems; there aren't penalties. Keep a good portion of capital for this. In the meantime, set up a program to buy the index each month irrespective of market prices. That way, we are in the markets all the time. When the price is right, buy the stocks, and hold for as long as the businesses are sustainable. The idea is to hold both stocks and index for a very long time, preferably more than a decade. Sell stocks when the underlying businesses no longer possess long term competitive advantages. When the selection is proper, such situations should be rare. Do not look for hot tips; do not follow anyone's stock portfolio. These are stupid ideas. Someone else's conviction will not do any good to us. Being in business is a long term game; so is being in stocks. 

Want to have fun? Go out and enjoy. Pick a book and read. Indulge in hobbies that make you happy. Want to trade in markets? Allocate an insignificant portion of capital, and speculate to glory. 

To make decent money from markets is not very difficult with right behavior. There isn't complicated math here. Think long; think long term, and it should be fine. And if we stop comparing ourselves with others, we should be fine too. 

Tuesday, September 4, 2018

how much can you make on nestle

Nestle India is worth Rs.1,060 b now. Based upon its reported earnings of 2017, never mind the subsequent nine months, of Rs.12 b, it works out to a pe multiple of over 85. It has never been quoted that high at least in the last decade. Sorry, it did once in 2015 when it was priced at a high pe of 128, and a low pe of 94 during the year. Even from a market price of Rs.723 b (high) in 2015, the annual market return to date is more than 15%. And it has effectively doubled in market value from its low price of Rs.530 b in 2015. 

Of course there was an anomaly because 2015 was an exceptional year for Nestle. There was a charge of Rs.5 b to its income statement due to the Maggi episode. If we remove this as one-off, the net earnings for 2015 would be Rs.10 b, and the high and low pe multiples fall to 68 and 50 respectively. That means, investors who bought in 2015 and sold now made money thus: buy at pe 68 or 50 and sell at 85 after a 15% rise in Nestle's earnings. Cool deal. But the catch is that if the pe multiple now is same as it was in 2015, i.e. 68, the returns would be paltry if bought at 68 times, and more than 15% if bought at 50 times.

I call this hope-based investing. When we rely entirely upon the multiple expansion rather than earnings and cash flows expansion, we need to sit and pray. 

Let's talk about good part of the story first. In 2007, Nestle's market cap was Rs.160 b (high) and Rs.84 b (low), and earnings were Rs.4 b. In 2012, it was Rs.484 b and Rs.378 b, and earnings were Rs.10 b. Investors benefited twice: earnings more than doubled during the period; and the pe multiples expanded from 38 (high) and 20 (low) to 45 (high) and 35 (low).

Now look at what happened during the subsequent five years. Earnings increased from Rs.10 b (2012) to Rs.12 b (2017); that is an annual increase of 2.79%. But the market value of equity more than doubled from Rs.484 b to Rs.1,060 b now. Nestle distributed about Rs.30 b in dividends in the past five years. 

Revenue growth has been 3.73% (5-year annualized) and 11% (10-year period). Earnings per share growth has been 2.79% and 11.47%. 

Let's make a bull-case scenario for Nestle. Let's assume that eps and dividends will increase at 12% per annum over the next 5 years; then eps would be Rs.224 per share in 2022. Dividends per share in 2017 was Rs.86. At the current price of Rs.11,277 per share, investors will lose close to 12% annually if we price the business at a pe multiple of 25 in 2022. There has to be some premium to the business, after all it is Nestle. Let's keep going. Even at the multiple of 45, investors will lose 1.20% annually over the 5-year period. At 50x, they will make less than 1%. At 60x, the investment returns will be less than 5%. Even at 80 times 2022 earnings, the returns will be 10.50%; the market index should be able to give that probably. If the expected return is say, 12%, the business should be priced more than 85 times earnings. 

Nestle's operating margins have been 17%. It also enjoys a very high return on equity and return on capital. The business does not require a lot of capital to operate. There has been no dilution in equity: 96.415 m shares have remained constant for a long time. Yet there is a moral in its story: A great business isn't always a great buy. There is a price for everything. Price is what you pay, value is what you get. 

Nestle has been generating solid free cash flows; for 2017, they were Rs.17 b. Nestle has not spent big on its capex other than in 2011 and 2012 for plant expansion. It is safe to assume that Nestle has the capability to generate average fcff of Rs.15 b annually. Although the growth rates in the past have been higher (5-year 20%; 10-year 17%), let's assume that fcff will grow at 12% over the next 5 years. If the expected returns are 12%, Nestle will have to be priced 70 times its 2022 fcff to get the present value of the 5-year cash flows equal its current market price.

Is it possible to earn decent returns from Nestle? Of course it is possible. But for that, investors will have to say prayers every day during their investment period: Oh, Lord, keep the pe up, and up. Is Nestle an exception? Of course not, there are lots of fantastic businesses priced egregiously by the market. Was it a buy in 2004? Heck yes.